

Subpilot
4.1

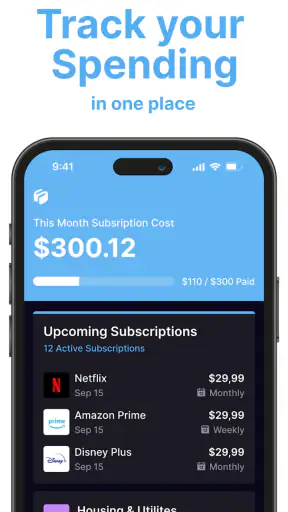
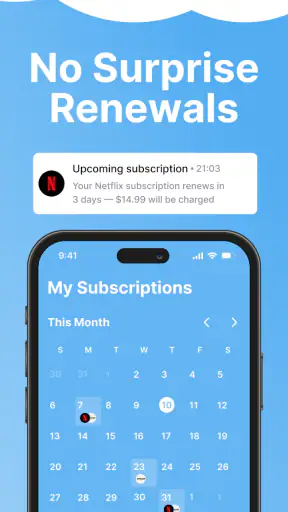
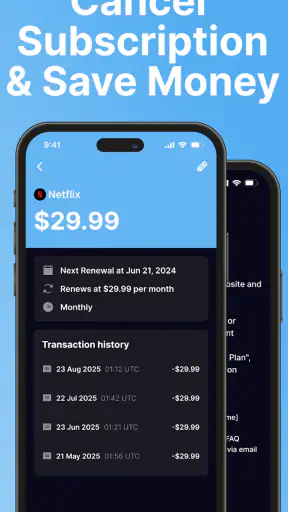
Managing subscriptions sounds simple until several small charges begin arriving from different services, app stores, cards, and payment accounts. That is the problem Subpilot tries to address. It is a free finance app from Linerios Limited focused on tracking and cancelling subscriptions, and I found its appeal less in flashy budgeting tools than in the promise of giving recurring spending a more visible place in my daily routine.
My first impression was that this is an app for people who have lost track of what renews automatically, not for someone looking for a complete replacement for a bank account or spreadsheet. That distinction matters. Subpilot is most useful when the question is, “What am I still paying for, and which of these services should I keep?” It is less compelling if you already review every statement manually and maintain a very disciplined list of renewals.
Where Subpilot fits in a personal finance routine
The app sits in a practical corner of personal finance: recurring-payment awareness. Rather than asking me to build a detailed household budget from scratch, it centers attention on subscriptions, the type of spending that is easy to forget because each individual charge may look harmless. A streaming plan, a cloud-storage tier, a fitness service, and an app membership can quietly become a meaningful monthly total when viewed together.
That focus gives Subpilot a clearer purpose than many broad finance apps. A traditional budgeting app may track income, bills, categories, investments, and savings goals, but subscriptions can become just another line among hundreds of transactions. A spreadsheet gives me control, yet it depends on remembering to update it. Subpilot is aimed at the gap between those approaches: enough structure to highlight recurring commitments without requiring me to maintain a full financial model.
The product is free to install, with optional in-app purchases ranging from $4.99 to $99.99 per item. I would treat that pricing structure as a reason to inspect the available choices carefully before committing to anything. The free entry point makes it easy to test whether the workflow actually fits my habits, while the range of purchase prices means I would not assume that every useful function is included at no cost.
Its audience is broad, reflected in an Everyone content rating, but the best match is more specific: people with several digital memberships, households where different services are paid through different accounts, or anyone who has been surprised by an automatic renewal. It can also help during a financial reset, such as moving to a new bank account, reducing monthly expenses, or reviewing spending after a period of frequent free trials.
What I would check before connecting anything
Trust is especially important in a finance app. A tool that helps me find recurring payments may need access to sensitive financial information or account-related details, depending on how its features work. I would therefore begin with the app’s visible permission requests, privacy explanations, and connection screens rather than rushing through setup. The key question is not simply whether the app is convenient; it is whether I understand what I am allowing and why.
I prefer a setup flow that explains each connection in plain language, shows which account or source is being used, and lets me stop before granting access. When reviewing Subpilot, I would pay close attention to whether each request is tied to a recognizable task, such as identifying recurring charges, instead of accepting broad access without reading. That habit is useful with any finance tool, but it matters even more when the app’s central value depends on seeing payment activity.
The developer is Linerios Limited, and the app has reached over one hundred thousand installs, with an average rating of 4.1 from around four thousand ratings. Those figures suggest that Subpilot has attracted a real user base, but they should not replace my own privacy check. Popularity can tell me that people are trying the app; it cannot tell me whether its access model suits my personal comfort level.
I would also avoid connecting every financial source immediately. A better approach is to start with the account most likely to contain the subscriptions I want to review. This creates a smaller test: I can see whether the results are understandable, whether recurring charges are presented in a useful way, and whether the app gives me enough control before expanding its reach. That staged setup is one of the most sensible ways to evaluate a finance app.
Finding forgotten renewals without creating new confusion
The strongest everyday use case is a subscription audit. Imagine noticing that the monthly total on a bank statement feels higher than expected. Instead of scanning a long transaction list and trying to remember every merchant, I would use Subpilot as a focused review space. I would look for services I still recognize, services I no longer use, and charges whose names are too vague to identify immediately.
The last group deserves special care. A merchant label may not match the brand name I remember, particularly when billing passes through an app store, payment processor, or parent company. I would not cancel anything solely because its label looks unfamiliar. I would compare the charge with email receipts, the relevant store account, and the service’s own billing page. Subpilot can help me notice a recurring payment, but I still need to verify what that payment represents before taking action.
A useful workflow is to review subscriptions in three passes. First, mark the services I actively use. Second, investigate anything unfamiliar or duplicated. Third, check whether the renewal timing still makes sense. This avoids the common mistake of treating every recurring charge as equally urgent. An annual service may not appear often but can still deserve attention before its next renewal, while a small monthly service may be easier to cancel immediately.
I would also use the app during a household review, but cautiously. If several people share financial responsibilities, one person may know the service while another controls the account that can cancel it. That makes ownership an important part of the process. A list of recurring charges is useful only when it leads to the correct account, the correct login, and a clear decision about who is responsible for the payment.
Cancellation is not always a single tap
The idea of cancelling subscriptions sounds straightforward, but the real process depends on where the subscription was purchased. A service started through an app store may need to be cancelled in the store’s subscription settings. A membership purchased on a website may require signing in there. A charge connected to a financial account may still be controlled by the merchant rather than the bank.
That is why I would judge Subpilot’s cancellation help by how clearly it guides me to the correct control, not by whether it makes the process appear magically universal. If the app points me toward the right place but still requires a final action in the merchant or store account, that is normal and preferable to pretending cancellation is complete when it is not.
After cancelling, I would save the confirmation and check the next statement or billing screen. Cancellation can stop future renewals without immediately reversing a recent charge, and a service may remain active until the paid period ends. This is a small but important distinction for anyone using a subscription manager: the app can organize the decision, but the merchant’s terms determine the final billing outcome.
There is also a practical trade-off between convenience and verification. A highly automated cancellation process may save time, but I would want a clear confirmation of what will happen, when access ends, and whether any data or account content is affected. For an unfamiliar service, I would rather spend an extra minute reading the final screen than cancel a plan I intended to keep.
Data-sensitive moments deserve slower decisions
Finance apps create several moments where I would deliberately slow down. The first is account connection. Before approving access, I would read the explanation, check the account shown on screen, and consider whether a manual review would be safer for my situation. The second is identifying a transaction. I would avoid entering extra personal details merely to make an ambiguous merchant easier to recognize unless the purpose is clear.
The third moment is removing access later. A trustworthy routine should include knowing how to disconnect an account or revoke permission when I no longer need the service. I would look for an obvious control inside the app and, where relevant, review the connected account’s own security settings. This is not a criticism unique to Subpilot; it is a standard precaution whenever a finance tool is given access to information that I would not share casually.
I would also be careful with shared devices. Because subscription information can reveal entertainment choices, health-related services, professional tools, or household spending patterns, I would not assume that everyone using the phone should automatically see it. A person who manages family bills may need the overview, while another person may prefer to keep individual purchases private. The app’s usefulness should not erase those boundaries.
Notifications deserve the same attention. Reminders can be helpful when they prevent an unwanted renewal, but too many alerts can become background noise. I would keep only the notices that support a real decision and silence anything that encourages me to open the app without a clear reason. The best finance reminder is one that arrives early enough to act and is specific enough to understand.
How much control does the user really have?
For me, user agency means being able to inspect, question, correct, and remove information rather than simply accepting an automated result. Subpilot is most valuable when it helps me make a decision while leaving the decision with me. I would want to review a detected subscription, correct an incorrect match, and distinguish between an active service, a cancelled service that has not yet expired, and a charge that needs investigation.
That distinction is especially important when a recurring payment is shared or reimbursed. A subscription may appear on my card but be used by several people, or it may be paid by a work account even though I use the service personally. In those cases, “cancel” is not automatically the right answer. I would first record who benefits from the service and whether another payment method should replace the current one.
A less obvious benefit of a dedicated subscription view is that it can change the timing of financial decisions. Instead of waiting for a monthly budget review, I can examine renewals before they happen. I would use that opportunity to ask three practical questions: did I use the service recently, would I sign up for it again today, and is there a cheaper or free alternative I already have? This turns the app from a passive list into a prompt for deliberate spending.
There is a limitation here: no automated list can understand the personal value of a service as well as I can. A low-cost app may be essential for work, while a larger charge may be worth keeping because it replaces several smaller tools. I would therefore avoid judging subscriptions only by price or frequency. The useful decision is whether the recurring commitment still matches my current needs.
Version, compatibility, and the practical ownership experience
Subpilot is currently at version 1.24.1 and requires Android 8.0 or later. That makes checking device compatibility a simple first step before planning a subscription audit. I would install it on the phone I actually use for financial tasks rather than treating it as a tool I might casually open elsewhere, because consistency matters when reviewing sensitive information and acting on renewals.
The app was released on September 2, 2025, so I would approach it as a relatively young product and pay attention to how steadily its controls and explanations evolve. A newer finance app can feel focused and modern, but it may also change its workflow as the developer responds to feedback. I would keep important cancellation confirmations and billing records outside the app instead of relying on any single interface to preserve my history.
Its review profile is encouraging enough to justify a trial, but not so strong that I would skip basic caution. Around one thousand seven hundred written reviews provide more useful context than a rating alone, especially if I read comments about account connections, recognition accuracy, cancellation guidance, and support responses. I would look for patterns rather than reacting to one unusually positive or negative comment.
The in-app purchase range also affects how I would evaluate it. I would first decide whether the free experience solves the problem I actually have. If I am only trying to identify a few forgotten subscriptions, paying for more tools may not be worthwhile. If I manage many recurring services and the paid option clearly saves repeated manual work, the calculation changes, but I would still check the billing interval and cancellation terms before purchasing.
Who should use it, and who should choose another method?
I would recommend trying Subpilot if recurring charges are scattered across multiple services and I want a single place to begin an audit. It is particularly suitable for someone who has recently accumulated several trials, changed payment cards, joined a number of digital services, or wants to reduce monthly commitments without building a full spreadsheet.
I would be more cautious about recommending it to someone who wants a complete budgeting system. If the main goal is forecasting cash flow, tracking debt, planning savings, or analyzing spending categories in depth, a broader finance app or a carefully designed spreadsheet may be a better fit. Subpilot’s narrow focus is a strength for subscription cleanup, but it is also the reason it should not be treated as an all-purpose financial dashboard.
I would also skip it if I am unwilling to connect financial accounts or review permission choices. A manual method may take longer, but it can offer more direct control: searching statements, checking store subscriptions, and maintaining a private list of renewal dates. That approach becomes especially attractive when my subscriptions are few, my billing sources are already organized, or the information involved is too sensitive for an additional service.
For people who do use it, I suggest a monthly or quarterly review rather than opening it constantly. Start with one account, verify unfamiliar charges, record the cancellation route, and keep evidence of completed changes. Then expand only if the results are accurate and the access remains comfortable. This workflow limits exposure while still capturing the app’s main benefit.
My cautious verdict after looking at the whole workflow
I see Subpilot as a focused finance companion rather than a replacement for careful account management. Its central idea is useful because recurring subscriptions are easy to overlook, and a dedicated review can reveal spending that disappears inside ordinary transaction history. The free starting point makes experimentation reasonable, while the Everyone rating and Android 8.0 compatibility make it accessible to many everyday users.
My recommendation comes with a clear condition: treat trust and control as part of the product experience, not as an afterthought. Read every connection screen, grant only what makes sense, verify unfamiliar charges, and confirm cancellations through the original merchant or store. Those steps may sound slower than the app’s main promise, but they are exactly what prevents convenience from turning into a new source of confusion.
Subpilot is worth trying when forgotten renewals are the problem you want to solve. I would choose it over a spreadsheet when I need a focused reminder to investigate recurring spending, but I would choose a broader budgeting tool when I need a complete view of my finances. Used carefully, it can make subscription cleanup more manageable; used blindly, no finance app can make sensitive account decisions safe on my behalf.
4.1
1.67K Reviews
Pros
- Automatically generates subtitles for videos and audio recordings.
- Supports multiple languages for broader accessibility.
- Useful for creating captions for social media content.
- Can save time compared with manually transcribing conversations.
- Simple workflow suitable for quick
- on-the-go editing.
Cons
- Transcription accuracy may drop with accents
- noise
- or overlapping voices.
- Processing longer files can take noticeable time or use more data.
- Some advanced features may require a paid subscription.
- Subtitle timing and wording may need manual corrections.
- Privacy concerns may arise when uploading sensitive recordings.


